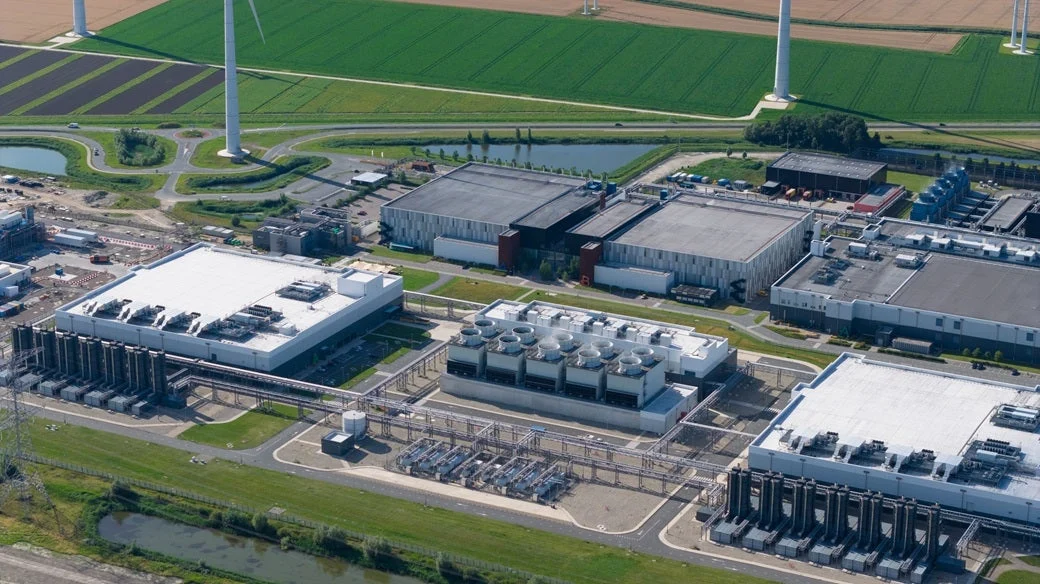
The global data centre market is currently undergoing a structural transformation that renders traditional forecasting models obsolete. For years, industry analysts relied on aggregate data, assuming that a pipeline consisting of thousands of projects would naturally smooth out volatility—where delays in one region or by one developer would be offset by accelerations elsewhere. However, new insights from GlobalData reveal that the data centre landscape is no longer a broad, distributed market; it is a highly concentrated ecosystem where the financial health and timelines of the entire sector hinge on a precarious "top-heavy" structure.
As the industry grapples with the immense power demands of artificial intelligence and cloud computing, understanding the market average has become a secondary concern. The real story lies in the individual mega-projects that hold the vast majority of the capital investment.
The Anatomy of Concentration: A Statistical Imbalance
To understand the current state of the global pipeline, one must look at the math behind the projects. Within the roughly 2,500 active projects currently tracked by GlobalData, the distribution of wealth is startlingly uneven. The top 4% of these developments account for approximately 40% of the total announced financial value. Even more extreme is the concentration at the very peak: the largest 1% of projects represent nearly 20% of the total investment value.
Conversely, the "long tail" of the market—comprising the smallest 40% of projects—accounts for a mere 4% of total capital. This creates a massive gap between the median and the mean project value. The typical median project sits at a valuation of approximately $350 million, yet the mean value is three times that amount. This statistical skew confirms that a small cohort of gargantuan campuses is pulling the average upward, effectively distorting the perception of market health.
Chronology of the Shift: From Distributed Growth to Mega-Scale
The evolution of this concentration can be traced back to the onset of the hyperscale era.
- 2018–2020: The market began to pivot toward large-scale cloud availability zones. While projects were increasing in size, they remained somewhat distributed across various regional hubs.
- 2021–2023: The "AI Boom" catalyzed a shift in requirements. The necessity for massive, high-density compute power forced developers to abandon smaller, incremental expansions in favor of massive campuses designed for future-proofing.
- 2024–2026: We have entered a period of "Transmission-Level Dependence." Because these mega-campuses require so much power, they can no longer rely on distribution-level grid connections. They require bespoke, transmission-level infrastructure, which has fundamentally altered the project development timeline.
Supporting Data: Why Statistics Fail the Current Market
When value is spread evenly across a market, forecast error is essentially a statistical event; the "law of large numbers" ensures that the total remains stable even if individual components fluctuate. However, in the current data centre landscape, forecast error is no longer statistical—it is existential.
If a handful of these massive campuses experience a delay of just 12 months, national and regional investment totals plummet immediately. These delays are rarely the result of poor planning; they are frequently driven by external systemic bottlenecks, specifically the "grid connection queue." Because these projects are so large, they are the first to be flagged by utility companies and the last to receive approval due to the sheer volume of transmission-level upgrades required.
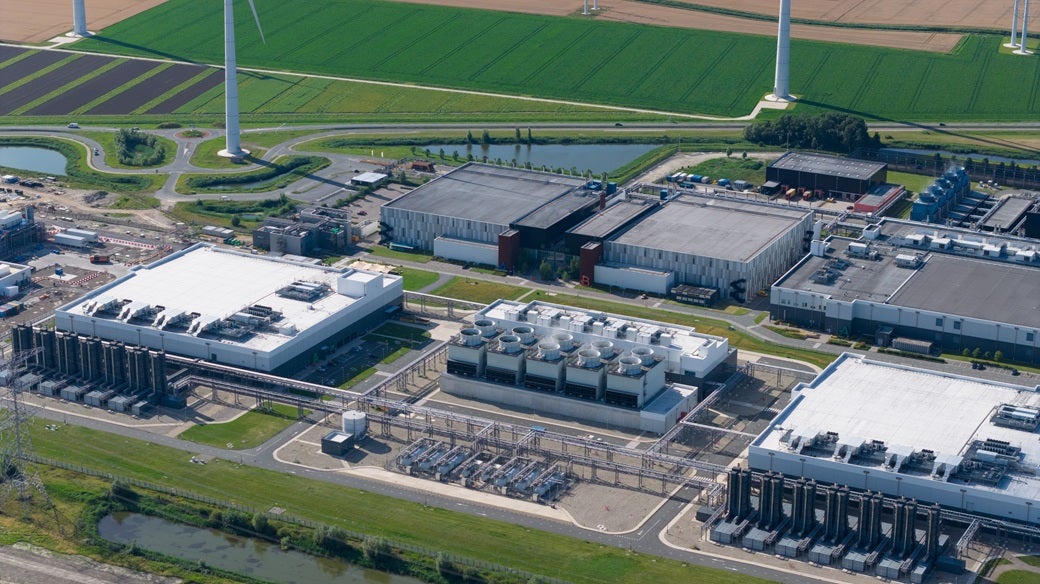
This creates a high-stakes environment where a single planning challenge, a change in an owner’s capital strategy, or a local environmental dispute can wipe billions of dollars from the short-term delivery forecast.
Analytical Dichotomy: Two Paths to Market Understanding
Given this concentration, industry analysts are being forced to adopt a two-pronged approach to market intelligence.
The Top-Tier Strategy (Individualized Analysis)
For the top 50 to 100 projects in the world, statistical analysis is virtually useless. To understand these, analysts must move away from "market sentiment" and toward "project-level forensics." This involves a granular investigation into:
- Ownership Dynamics: Who is the sponsor, and what is their current cost of capital?
- Power Security: Has the developer actually secured a signed grid connection agreement, or are they still in the queue?
- Permitting Status: Has the project cleared local planning hurdles, or is it vulnerable to political or community litigation?
- Activity Velocity: Has the project’s reported timeline moved recently, or has it been stagnant for more than two quarters?
The "Long Tail" Strategy (Broad-Market Analysis)
For the remaining 95% of projects, the approach must be reversed. Because no single small project carries enough weight to move the market needle, these projects should be viewed collectively. The value here lies in identifying regional trends and the participation of smaller, independent operators. If the "long tail" is growing, it indicates that demand is genuinely broadening across the economy, rather than being concentrated solely in the hands of a few dominant tech giants.
Implications for Investors and Stakeholders
The implications of this concentration for developers, investors, and power providers are profound.
Project Risk vs. Market Risk
For those underwriting these developments, the risk is no longer "market risk"—the danger that demand for data storage will decline—but "project risk"—the danger that a specific development will fail to reach the finish line. When an addressable pipeline depends on a handful of named schemes, investors must treat their portfolios with the rigor of a project finance lender. Tracking the "market average" is a trap; it provides a false sense of security while ignoring the specific, named risks that could lead to a catastrophic delivery failure.
The Valuation Gap
The concentration of the market also creates a two-tier valuation system. The largest campuses are subject to intense scrutiny, with their valuations heavily contested by grid availability and capital costs. Meanwhile, the "tail" is where specialist developers and regional operators function. Here, competitive dynamics are localized and valuations are often more stable, as these projects are less sensitive to national grid-level disruptions.
Official Perspective: The Deliverability Gap
The industry is currently facing what experts term the "Deliverability Gap." This is the discrepancy between the amount of data centre capacity announced and the amount that is actually capable of coming online by 2030, given the current constraints of the global energy grid and the construction labor market.
GlobalData’s latest whitepaper, The Deliverability Gap, highlights that the pipeline is not a homogenous list of assets. Every project must be weighted by its current stage and activity levels to truly understand its probability of completion. As the report notes, the data centre market is no longer a passive utility-style investment; it is a high-velocity, high-risk sector that requires specialized, project-by-project surveillance.
Conclusion: A New Era of Intelligence
The era of broad-brush data centre forecasting has ended. As the capital required for these projects reaches unprecedented levels, the market has become increasingly fragile, dependent on the successful execution of a few massive, complex campuses.
Stakeholders who continue to rely on aggregate market trends will find themselves increasingly disconnected from reality. The future of data centre intelligence lies in the ability to distinguish between the noise of the long tail and the strategic significance of the few dozen projects that will define the digital infrastructure of the next decade. For those looking to mitigate risk and identify real growth, the message is clear: look past the average, and focus on the individual project.
For those interested in a deeper analysis of these trends, the GlobalData Data Centre Projects Database offers individual tracking for all 2,500 developments, providing the granular data necessary to navigate this concentrated landscape. Download the full whitepaper, The Deliverability Gap, to see how project-level weighting alters the outlook for 2030.